Business Planning in Virginia Beach & Hampton Roads
Protect the business you built, your family and your exit. Call (402) 649-1418 to schedule your consultation.
Business Succession and Continuity Planning for Hampton Roads Owners
Business planning helps owners protect the company they have built and plan for the day they step away, whether by choice, retirement, disability or death. Legacy Solutions Estate & Income Planning works with small business owners across Virginia Beach and Hampton Roads to fund buy-sell agreements, protect against the loss of a key person, plan a succession and coordinate the business with the owner’s personal retirement and estate plan.
For many owners, the business is their largest asset, so it needs to be part of both the retirement and the estate plan.
A buy-sell agreement sets the terms for what happens to an owner’s share. Life insurance is often used to make sure the money is there to carry it out.
Key person insurance helps a business survive the loss of an owner or critical employee.
Succession planning works best when it starts years before the owner plans to leave.
What Happens to Your Business If Something Happens to You?
For many small business owners, the business is both the household income and the largest asset in the estate. If an owner dies, becomes disabled or wants to retire without a plan, the result can be a forced sale, disputes between partners and heirs, or a business that loses its value before anyone can decide what to do.
A business continuity plan answers the hard questions in advance: who can buy an owner out, how the business will be valued and where the money will come from. Planned well, it protects your employees, your partners and your family while giving you a clear path to retirement.
Call (402) 649-1418 or fill out the form below to schedule your business planning consultation.
What Is Business Succession Planning?
Business succession planning answers a hard question: what happens to the business, its employees and your family if you are no longer running it? Without a plan, a sudden death or disability can force a quick sale at a low price, leave partners in business with an owner’s spouse or heirs, or put the company at risk while everyone sorts things out.
A complete plan covers both the planned exit and the unplanned one. It sets out who will take over, how the business will be valued, where the money for a buyout will come from and how the proceeds fit into your retirement income and estate plan.
Who Needs Business Planning?
Small business owners whose family depends on the income or value of the business.
Partners and co-owners who need a funded agreement for what happens if one owner dies, becomes disabled or wants out.
Family businesses planning to hand the company to the next generation.
Owners nearing retirement who want to turn the value of their business into retirement income.
Veterans and military spouses who have started businesses in Hampton Roads.
Businesses that depend on one person whose loss would put revenue or loans at risk.
How the Business Planning Process Works
Education first. We explain the common ways businesses change hands and how each affects you, your partners and your family.
Understand your business. We review your ownership structure, existing agreements, rough value and how the business supports your household.
Identify the risks. We look at what would happen if you or a key person died, became disabled or left suddenly.
Recommend solutions. These may include funding a buy-sell agreement, key person coverage, disability buyout coverage and a timeline for succession.
Coordinate the team. We work with your attorney, CPA and business valuation professional so legal agreements, taxes and funding line up.
Core Business Planning Tools
Buy-sell agreements. Drafted by your attorney, a buy-sell agreement spells out who can buy an owner’s share, how it will be valued and when a sale is triggered. Life insurance or disability buyout coverage often provides the funds.
Key person insurance. A policy owned by the business on a critical owner or employee can cover lost revenue, recruiting costs or loan obligations if that person dies.
Succession planning. Whether you sell to a partner, employees, family or an outside buyer, a written plan and timeline protect the value of the business.
Personal planning for owners. Your exit should support your retirement income plan, and your business interest needs to be addressed in your estate plan so your family is not left guessing.
What to Bring to Your First Meeting
Your business formation documents and any operating, partnership or shareholder agreement
Any existing buy-sell agreement and related insurance policies
Recent business financial statements or tax returns
A list of owners and key employees
Your personal estate planning documents and retirement account statements
Planning for Veteran-Owned Businesses
Hampton Roads is home to many veteran- and military spouse-owned businesses. Frequent moves, deployments and the transition from military to civilian life can make continuity planning even more important. Shannon understands those realities and helps owners build plans that hold up when life changes quickly.
Serving Virginia Beach and All of Hampton Roads
Legacy Solutions Estate & Income Planning is based in Virginia Beach and works with business owners throughout the 757, including Virginia Beach, Norfolk, Chesapeake, Portsmouth, Suffolk, Hampton and Newport News. We also host free educational workshops. See our upcoming events or explore all of our services.
Legacy Solutions Estate & Income Planning
2 Constitution Drive, Suite 101, Virginia Beach, VA 23462
Phone: (402) 649-1418
This page is for general educational purposes. Legacy Solutions Estate & Income Planning does not provide legal, tax or investment advice. Consult a licensed attorney, tax professional or financial advisor about your specific situation.
Business Planning Guidance From Shannon Raitt
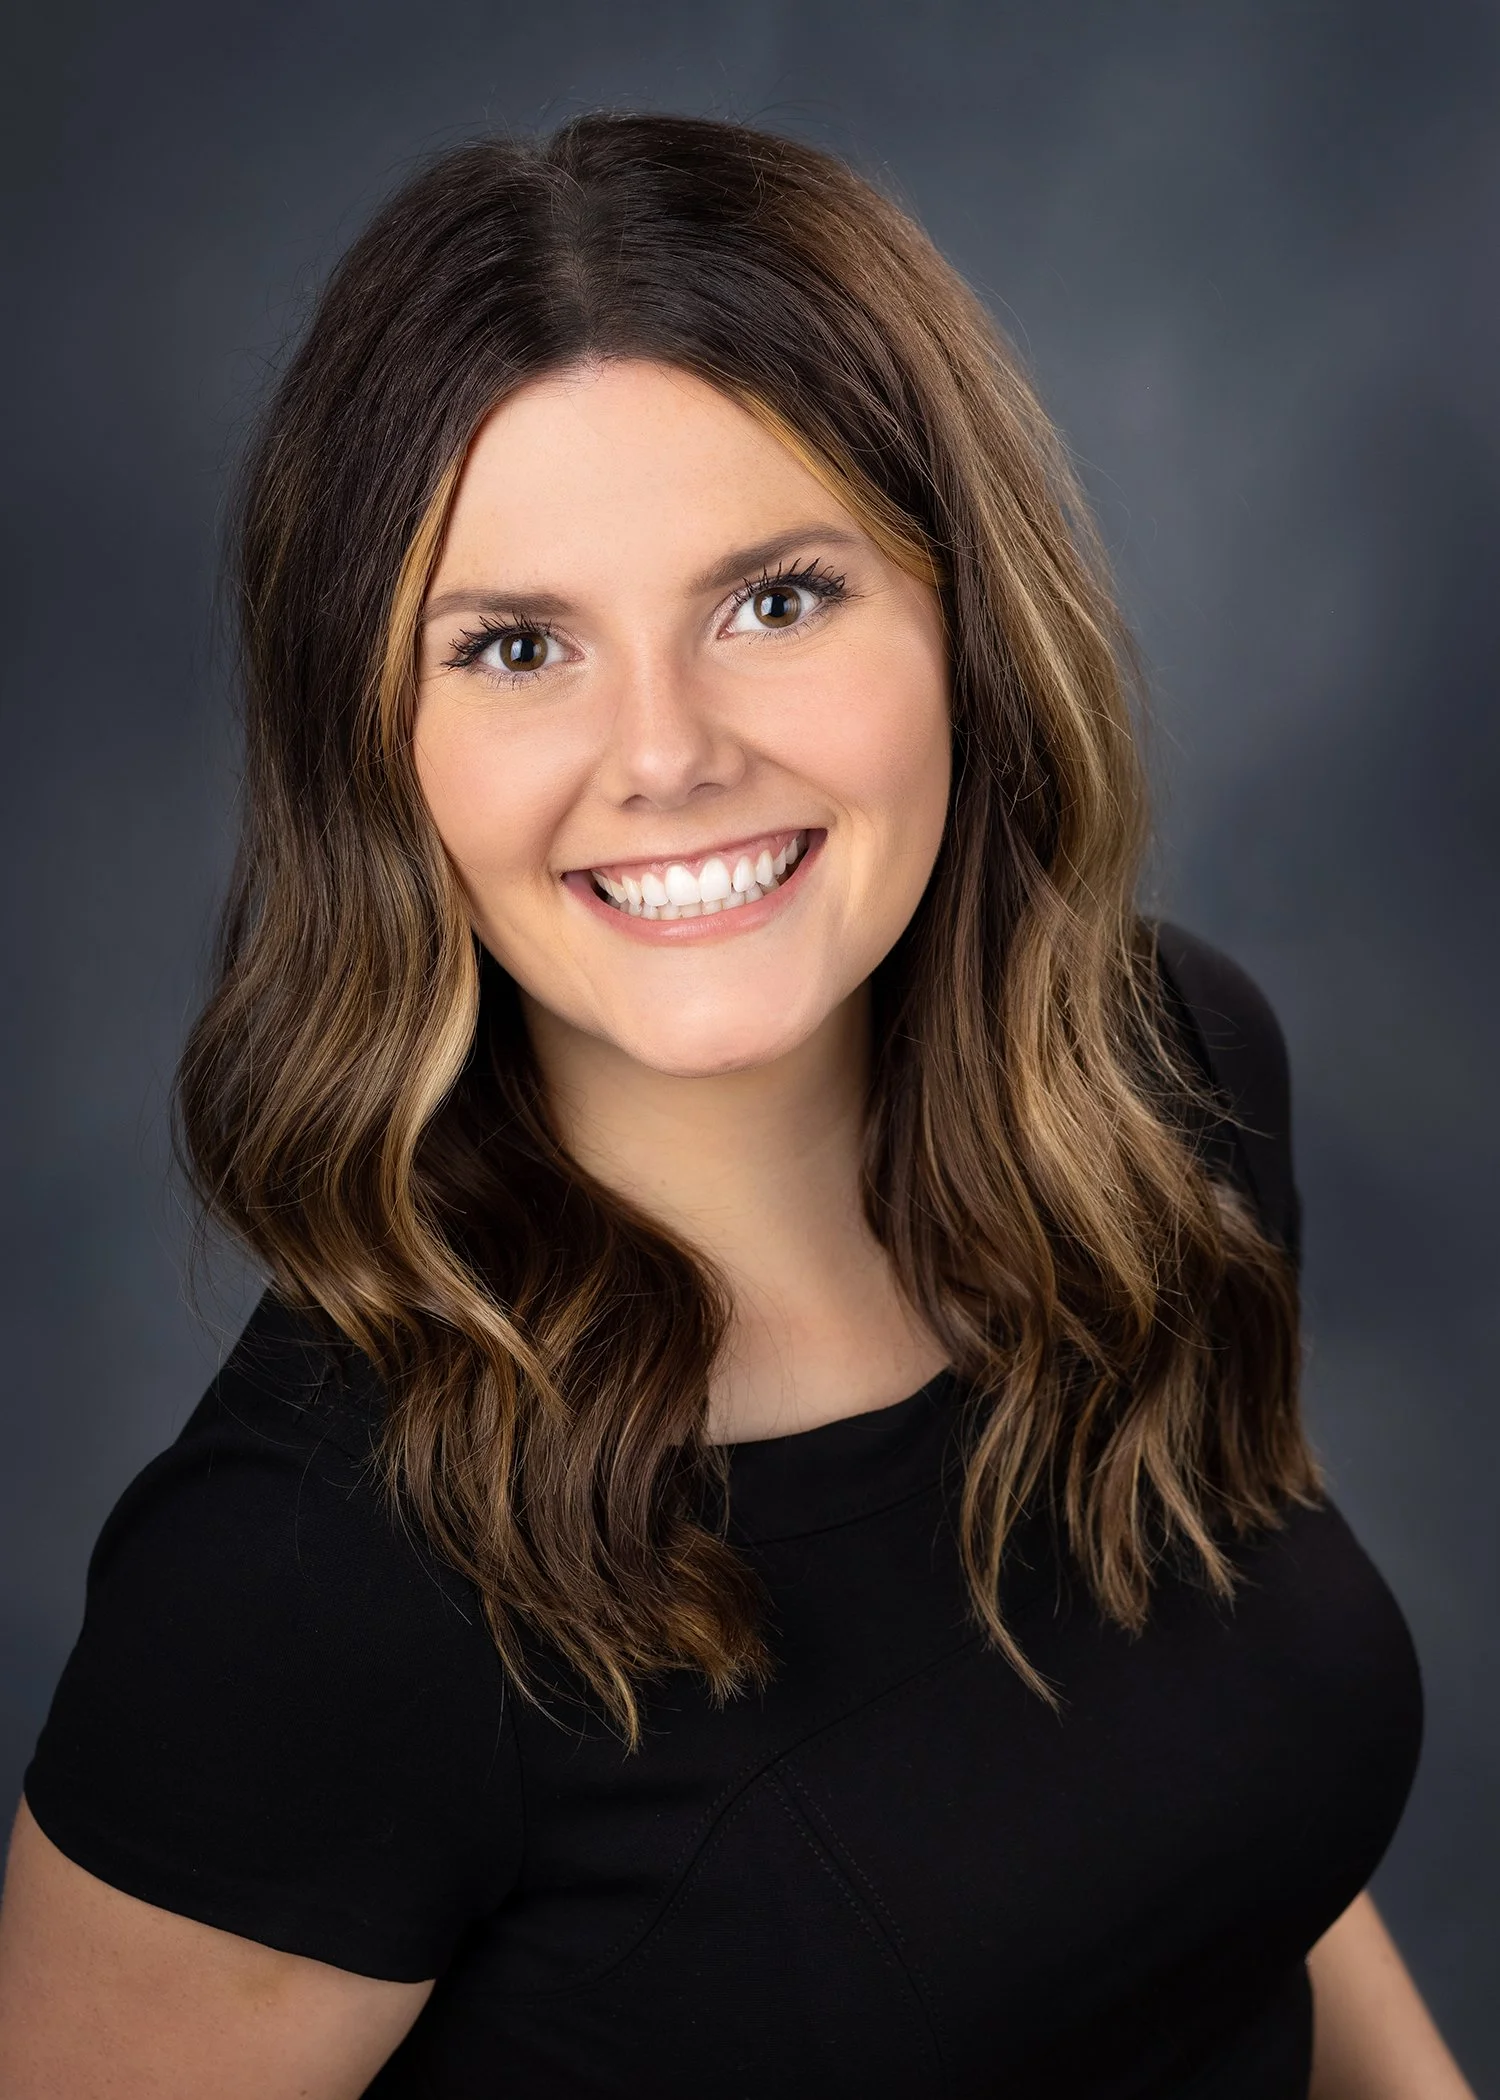
Shannon Raitt works with small business owners across Hampton Roads to plan for continuity and succession, including funding buy-sell agreements and key person coverage. As part of a second-generation, family-owned firm, she understands what is at stake when a business passes to the next owner, and she coordinates with your attorney and CPA at every step.
Business Planning FAQs
-
A buy-sell agreement is a legal contract among business owners that sets the rules for buying an owner’s share after a death, disability, retirement or departure. Your attorney drafts the agreement. We help make sure the money to carry it out is in place, often through life insurance.
-
It is life or disability insurance owned by the business on someone whose loss would seriously hurt the company. The benefit is paid to the business to help it replace lost income, recruit a successor or pay down debt.
-
Ideally five to ten years before you want to leave. That gives you time to build value, train a successor and plan the tax side of a sale. A plan for an unexpected death or disability should be in place now.
-
Your ownership interest has to pass to someone. Your estate plan, any trust and your buy-sell agreement should all agree on who that is and how it happens. Learn more about our estate planning services.
-
Often, yes. We help you estimate what the business could provide and build it into a retirement income plan along with Social Security and savings. Learn more about retirement income planning.
-
No. Business valuations are done by qualified valuation professionals, and agreements are drafted by your attorney. We coordinate with them and focus on funding, risk management and how the business fits your personal plan.
Schedule Your Business Planning Consultation
Tell us a little about your situation and we’ll follow up to set up a time to talk. Prefer the phone? Call (402) 649-1418.